How to Onboard Trusts, LLCs and Entity Investors in a Syndication
 Jacob BlackettLast Updated: Nov 20, 2026
TL;DR
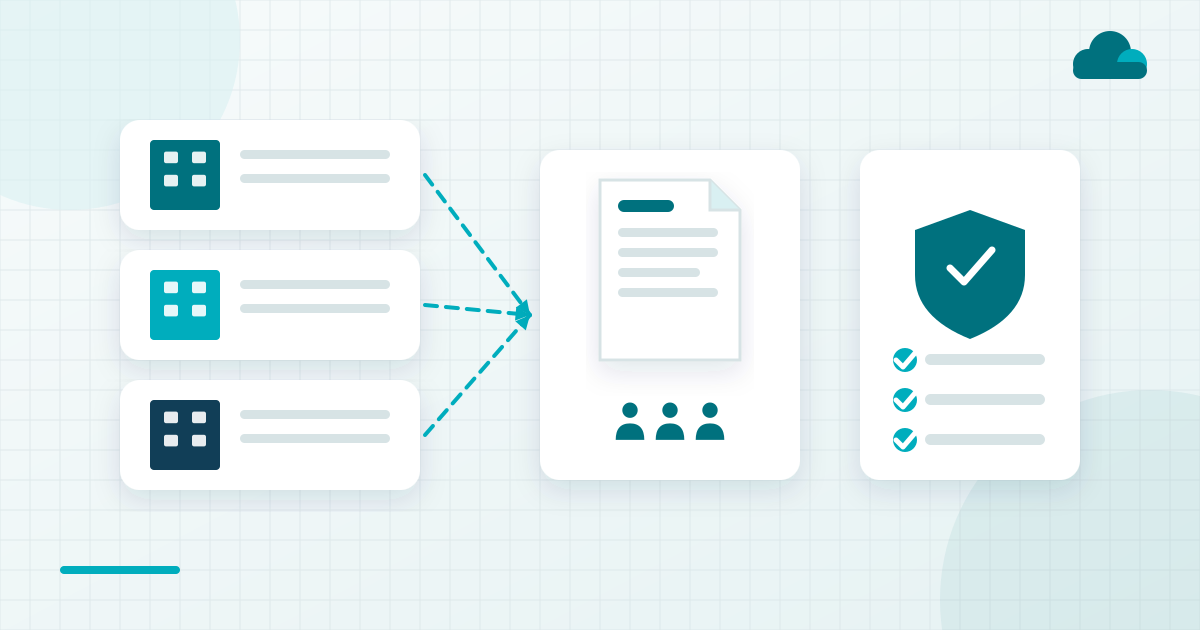
- An entity investor invests in its own name, so the sponsor records the entity as the investor of record and links the people who sign and act for it.
- Onboarding an entity adds four checks to an individual's onboarding, covering signer authority, formation documents, the people who own or control the entity and its tax form.
- Accreditation works differently for entities, and the Securities and Exchange Commission (SEC) lists separate paths for them, including an asset test and a path where every equity owner is accredited.
- A U.S. entity usually provides a Form W-9 with its own taxpayer identification number (TIN), and a foreign entity provides a Form W-8BEN-E.
- Because the entity is the partner, its distributions are paid to an entity account and its Schedule K-1 carries the entity's name, so the record needs the entity's legal name and tax details.
- SponsorCloud's investor platform keeps investment records with ownership and allocation information for every investor. This page is general guidance and is not legal or tax advice.
To accept an investment from a trust or limited liability company (LLC), a sponsor records the entity investor in its exact legal name and confirms who may sign for it from its trust or operating documents. The sponsor then collects formation documents, identifies who owns or controls the entity, confirms its accreditation path and takes its tax form.
Distributions and the K-1 go to the entity.
An entity investor is a trust, LLC, partnership, corporation or other legal entity that invests in a real estate syndication in its own name, through a person authorized to sign for it. Onboarding an entity investor means confirming who may sign, what the entity is, who owns or controls it and how it reports for tax, before its ownership is recorded.
What Changes When the Investor Is an Entity
Entity investors arrive as a sponsor's investor base grows. Capital sources widen from accredited individuals to trusts, LLCs, partnerships and retirement plans, and each new type brings its own paperwork to the subscription.
With an individual, the investor and the signer are the same person. With an entity, the entity is the investor and a person signs for it, so every later step depends on recording both correctly. The limited partner (LP) in the deal is the entity, and the person the investor relations (IR) team emails is its signer.
Most of the extra work happens once, at the first subscription. After that the entity behaves much like any other investor, as long as its record stays current.
Retirement accounts, such as a self-directed individual retirement account (SDIRA), invest through a custodian and follow a path of their own that sits outside this article. The steps below cover trusts, LLCs, partnerships and corporations investing directly.
How to Accept an Investment from a Trust or LLC
Accepting an investment from a trust or LLC runs through eight steps, in the order below. Each step describes general practice, and every legal point in it is something the sponsor confirms with counsel for its own offering.
Record the Entity as the Investor of Record
Record the subscription in the entity's exact legal name, as it appears on its formation documents and its tax form. The individual who introduced the investment is linked to the entity record as a contact, and the entity stays the investor of record.
The name entered at this step is the name that appears on every distribution and every K-1 that follows. A shortened name or a personal name in its place creates a correction later, often at K-1 season.
Confirm Who Can Sign for the Entity
Confirm who may sign before the subscription documents go out. For an LLC, the operating agreement or a written resolution names the signer, usually a manager or managing member. For a trust, the trustee signs, often supported by a certification of trust.
For a corporation, a board resolution or an officer's authority covers the signature. Counsel decides what evidence of authority the sponsor accepts, and the signer is recorded as a contact linked to the entity.
Collect the Formation Documents
Collect the documents that show the entity exists and how it is governed. For an LLC that usually means the certificate of formation and the operating agreement, or the pages of it the sponsor's policy requires. For a trust it means the trust agreement or a certification of trust.
Where an operating agreement runs long, sponsors often accept the pages that name the members and managers, with counsel's agreement. Store the formation documents with the investor record. The IR team then finds them when the entity invests again or a question comes up at K-1 season, without asking the investor to send them twice.
Identify the People Who Own or Control the Entity
Identify the individuals who own or control the entity investor under the sponsor's know your customer (KYC) and anti-money laundering (AML) policy. What the sponsor collects, and from whom, is set with counsel.
The bank receiving the funds, or a broker-dealer involved in the offering, may ask for the same information. Federal beneficial ownership reporting requirements have changed in recent years, so counsel confirms what applies to the offering when the raise opens.
Confirm How the Entity Qualifies as Accredited
Confirm the entity's accreditation path, because the SEC lists separate paths for entities. Corporations, partnerships, LLCs and trusts may qualify with assets over $5 million, subject to conditions the SEC sets out, such as not being formed to buy the securities offered, and an entity may qualify when all of its equity owners are accredited investors.
A trust relying on its assets has further conditions to meet, which counsel confirms. In a Rule 506(c) offering every purchaser must be accredited, and the issuer takes reasonable steps to verify that status. The verification method for an entity stays with counsel.
Collect the Entity's Tax Form
Collect the entity's tax form before the first distribution. The Internal Revenue Service (IRS) describes Form W-9 as the form for giving a TIN to a person who must file an information return, and an entity formed in the United States usually provides its own number.
A foreign entity uses Form W-8BEN-E to document its status. Some entities report under another party's number, such as a single-member LLC disregarded for tax or a trust reporting under its grantor, and the sponsor's certified public accountant (CPA) confirms which number belongs on the record.
Set Up Distributions to an Account in the Entity's Name
Set distribution instructions to an account in the entity's legal name, matching the name on the investor record. Any change to bank details is confirmed with the authorized signer directly before it takes effect, using contact details already on file. Instructions for an entity are worth a second check at the first payment, since a mistake repeats on every payment after it.
A payment for an entity's investment sent to an individual's account blurs who owns the position. It also leaves the distribution record out of step with the K-1 the entity receives.
Send the K-1 to the Entity
Send the Schedule K-1 to the entity, because the IRS has each partnership furnish a K-1 to each partner and here the partner is the entity. The K-1 carries the name and number from the entity's tax form, so the investor profile has to be right before K-1 season.
An investor profile audit ahead of the season catches a wrong name or number while it can still be fixed quietly. Confirm reporting specifics with a CPA.
What Documents an Entity Investor Provides
Sponsors commonly request the documents below from entity investors, and the sponsor's counsel sets the final list for each offering.
- LLC. The certificate of formation, the operating agreement or its relevant pages, evidence of who may sign and Form W-9 or W-8BEN-E.
- Trust. A certification of trust or the relevant pages of the trust agreement, with identification for the trustee. The trust's Form W-9 or W-8BEN-E.
- Partnership or corporation. Formation documents and a resolution or partnership authority for the signer, with the entity's tax form.
- Every entity. Accreditation evidence as the offering requires, and identification of the people who own or control it under the sponsor's KYC policy.
Publishing the list at the start of the raise lets an entity investor gather its documents before the subscription goes out. Investors remember whether documents were easy to find and whether someone answered, and a list sent early answers the first question before it is asked.
Some entity investors will have invested with the sponsor before. Their documents already sit on the record, so the request for a new deal can ask only for what has changed since.
How to Keep Investor Records for Entity and Trust Investors
Keep one investor record per entity, linked to the people who sign and act for it. One person may control several entities and invest personally as well, so the sponsor sees all of those positions together while each stays separate.
Ownership and allocation are recorded against the entity, and distributions and K-1s follow it. Entity records change over time, such as a new trustee or a transfer to another entity, and the record is updated before the next distribution and K-1.
Manual records compound small errors as the investor count grows. A stale signer or an old account number on an entity record surfaces at distribution time, when it is hardest to fix.
Changes to an entity can arrive mid-hold, such as a trustee who steps down. The sponsor collects the new signer's authority the same way it collected the first, and the record keeps the history so earlier distributions still show who signed at the time.
SponsorCloud is an investor platform, customer relationship management (CRM) and growth system for commercial real estate (CRE) sponsors. Its investment management software for ownership records keeps investment records with ownership and allocation information and runs distributions and K-1 workflows from them. Its real estate tax services for K-1s and investor profile audits include investor profile audits as part of the K-1 service.
For the general onboarding workflow on the platform, see SponsorCloud investor onboarding software.
How to Prepare for Entity Investors Before the Next Raise
Prepare for entity investors by agreeing with counsel which documents the sponsor accepts for each entity type. Publish that list to investors at the start of the raise, and audit existing entity records before the next distribution.
Entity investors meet a sponsor's back office at subscription, well before their first distribution, so a clear list and clean records shape their view of the raise from the first document.
This page is general guidance and is not legal or tax advice, so confirm accreditation and signer authority with securities counsel and tax reporting with a CPA. To see how investment records and ownership information work in an investor platform, schedule a consultation with SponsorCloud.
FAQs
How Does a Sponsor Accept an Investment from a Trust?
The trust is recorded as the investor in its exact legal name, and the trustee signs the subscription documents. Sponsors commonly ask for a certification of trust or the relevant pages of the trust agreement, along with the trust's tax form. Counsel sets the final list, which may add identification for the trustee, and this answer is general guidance and is not legal advice.
Who Signs Subscription Documents for an LLC Investor?
The person the LLC's operating agreement or a written resolution authorizes to sign, usually a manager or managing member. Sponsors ask for evidence of that authority with the subscription and record the signer as a contact linked to the LLC, which stays the investor of record. Counsel decides what evidence the sponsor accepts.
How Does an Entity Qualify as an Accredited Investor?
The SEC lists separate paths for entities, and corporations, partnerships, LLCs and trusts may qualify with assets over $5 million when not formed to buy the securities offered. An entity may also qualify when all of its equity owners are accredited, and a trust relying on assets has to meet the SEC's other conditions.
What Tax Form Does an Entity Investor Provide?
An entity formed in the United States usually provides IRS Form W-9 with its taxpayer identification number, which the IRS describes as the form for giving that number to a person who files an information return. A foreign entity provides Form W-8BEN-E. How a particular trust reports is a question for the sponsor's CPA, and this answer is not tax advice.
Who Receives the K-1 When an LLC or Trust Invests?
The entity does, because it is the partner, and the IRS has each partnership furnish a Schedule K-1 to each partner, so the K-1 carries the name and taxpayer identification number from the entity's tax form. That is why the investor record needs the entity's exact legal name and tax details before K-1 season. Confirm reporting specifics with a CPA.
Does a Sponsor Need to Identify the Owners of an Entity Investor?
Sponsors commonly identify the individuals who own or control an entity investor as part of their know-your-customer policy. The bank receiving funds or a broker-dealer involved in the offering may also ask. What the sponsor collects, and how, is set with securities counsel, since requirements depend on the offering and the parties involved.
Jacob Blackett
CEO and Co-Founder, SponsorCloud
Jacob Blackett is the CEO and co-founder of SponsorCloud. He raised capital and ran commercial real estate as a sponsor before he built software for other sponsors, and he still manages funds today. He built the platform that became SponsorCloud to solve problems in his own raises, tested it against real capital and real deadlines across his own portfolio, and then opened it to other GPs.
Related Signals
How to Handle an LP Who Wants to Sell or Transfer Their Interest
Jacob BlackettThu, Nov 19, 2026
What Every LP Capital Account Statement Should Show, Line by Line
Jacob BlackettThu, Nov 19, 2026
How to Give LPs One View Across Every Deal They Have With You
Jacob BlackettWed, Nov 18, 2026